Day Trading Mastery: Expert Tactics
Day trading requires a repeatable process for choosing setups, sizing exposure, managing orders, and reviewing results within a defined trading session. Chart patterns and discipline can support that process, but neither establishes a profitable edge by itself. Trading costs, liquidity, execution, and the quality of your testing all matter.
With LuxAlgo’s native charts, you can examine price and volume, use Quant, our coding agent, to develop a testable strategy, and review recorded trades in the Journal. The workflow below connects technical analysis, risk management, psychology, and technology without treating an indicator signal or AI-generated backtest as a promise of success.
Prepare the Session Before Choosing an Entry
Start with the exact market, venue, timeframe, and hours you intend to trade. Define the latest time for new entries and how open positions and pending orders will be handled before your session ends. In a continuously traded market, choose an explicit cutoff rather than assuming there is a universal closing bell.
Check the spread, recent trading activity, scheduled announcements, and whether your intended size can reasonably be executed. A narrow stop can look attractive mathematically while being unrealistic after spread and slippage. An instrument that moves quickly is not automatically suitable for your capital or method.
Confirm your broker’s current account permissions, margin requirements, and available order types for that instrument. Chart access is separate from permission to trade. If short selling is part of the plan, account for borrow availability and costs rather than assuming every short signal is executable.
Technical Analysis: Give Each Timeframe a Job
Choose a small number of timeframes with distinct purposes. For example, a one-hour chart can provide context, a 15-minute chart can define a setup area, and a five-minute chart can govern entries. These are illustrative choices, not an optimal ratio. Weekly and daily charts may add background, but a multiweek rally does not validate an intraday entry method.
| Layer | Question | Example rule to define |
|---|---|---|
| Context | What conditions permit the strategy? | A direction condition using the latest completed one-hour candle |
| Setup | Where might a trade become interesting? | A previously identified level or a range formed during specified hours |
| Trigger | What observable event creates an entry? | A completed five-minute close beyond the level |
| Execution | When and how is the order submitted? | A next-bar order with explicit size, stop, and cancellation rules |
The higher-timeframe candle still forming can change before it closes. Do not use its eventual closing value for an earlier decision. Likewise, a swing point confirmed by subsequent bars was not known with that confirmation on the pivot bar. Record the information available when the signal actually occurred.
LuxAlgo’s chart layouts let you compare markets or timeframes, with symbol, interval, and crosshair synchronization controlled independently. For one market across several intervals, synchronize the symbol and leave intervals independent. Check the active chart before applying an indicator or Quant script.
Read Volume Profiles Without Confusing the Terms
A volume profile summarizes traded volume by price over a chosen window. A high-volume node is a local concentration of volume; a low-volume node is a relative trough. Neither directly measures the resting liquidity available for your next order.
The value area is different from a high-volume node. It is a region selected to contain a specified share of the profile’s volume, commonly 70%. The point of control is the highest-volume price row. A 70% setting is not a 70% probability that price will stay inside the area or that a trade will succeed.
In LuxAlgo’s native volume profiles, Session and Rolling use footprint data on supported symbols. Visible Range uses candle volume and recalculates when you pan or zoom; its up/down colors do not classify buy/sell aggressors. Keep the chosen window consistent when comparing setups.
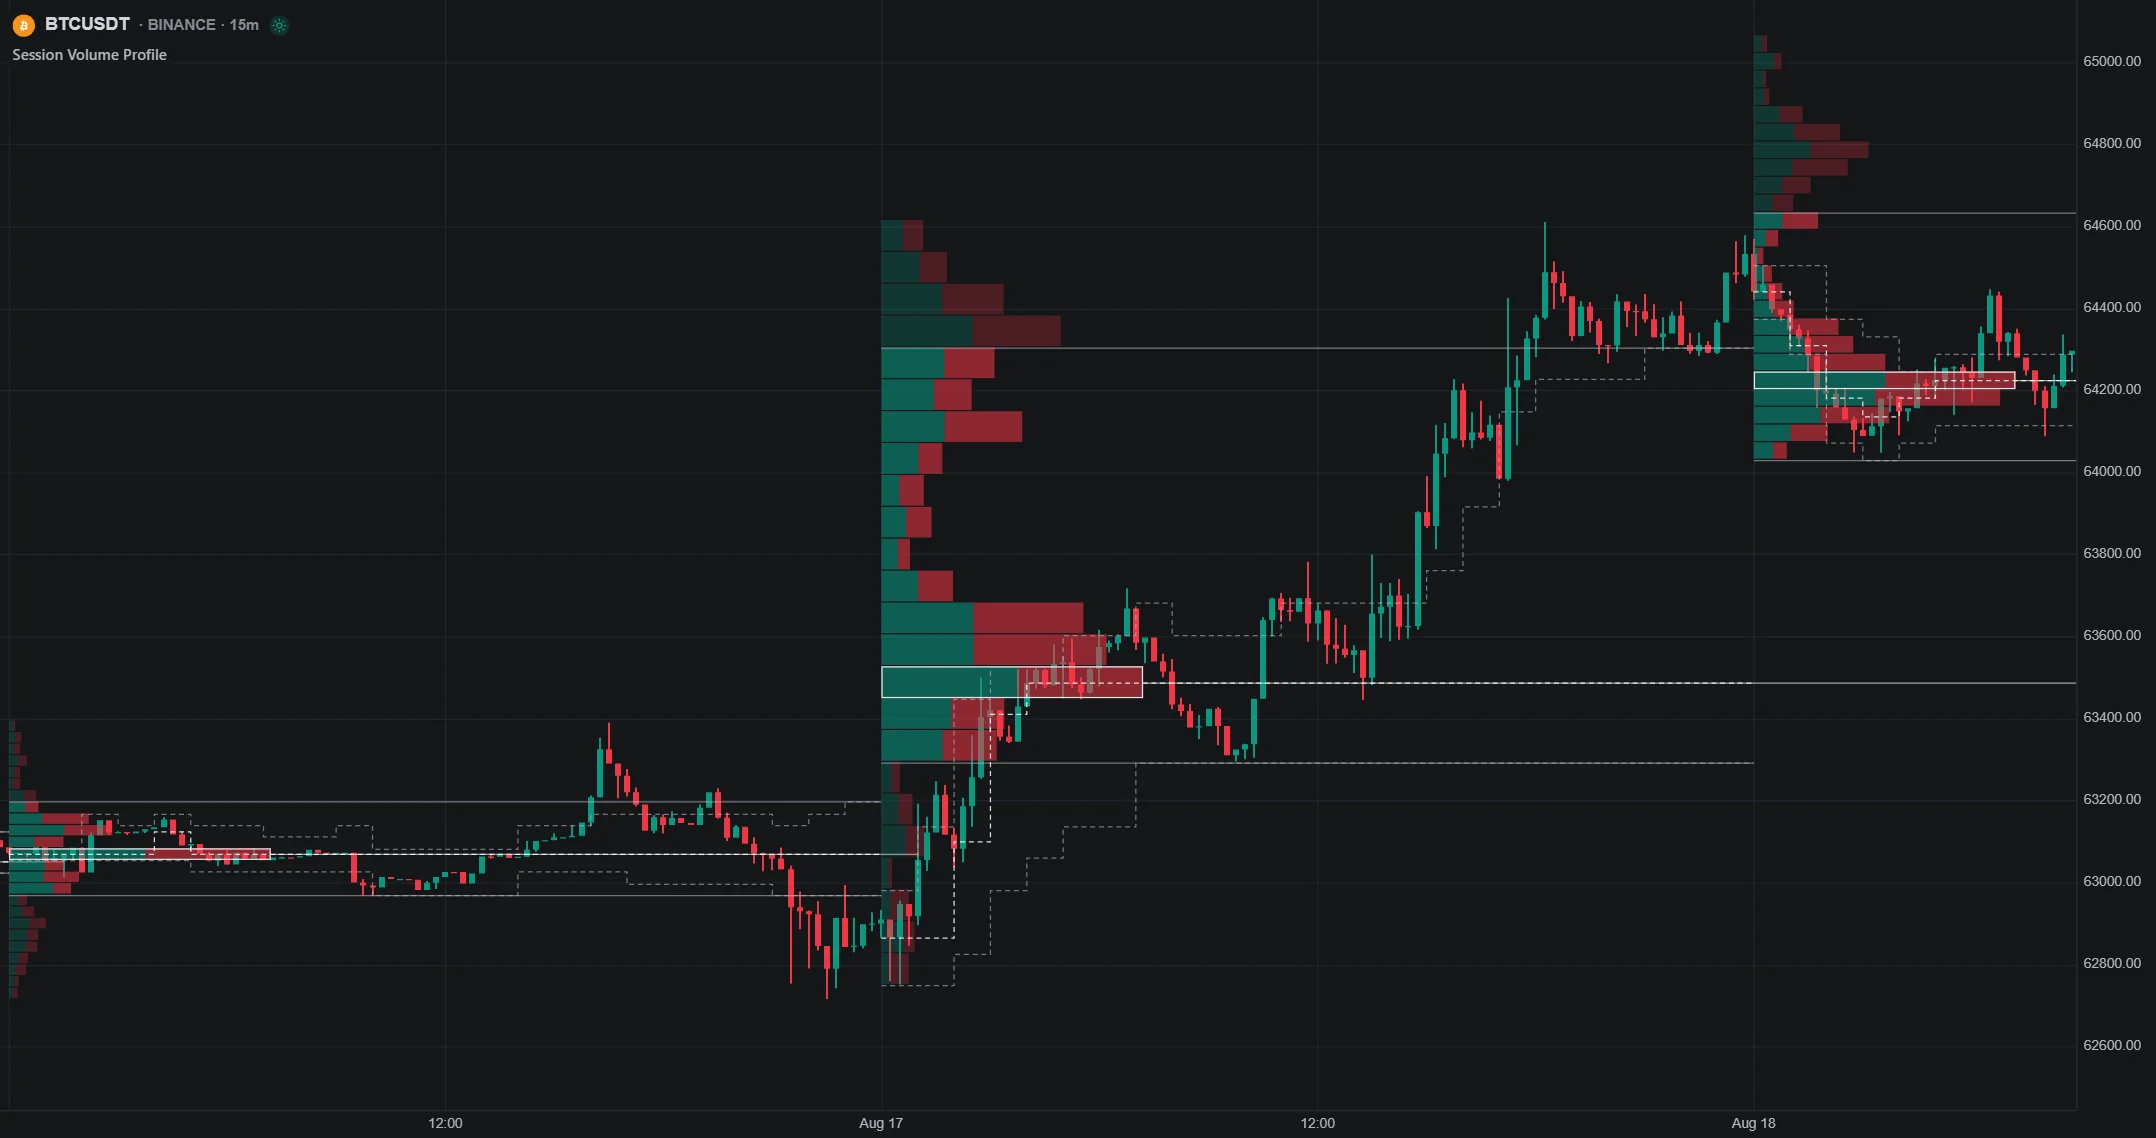
Final session levels include the entire session. For an earlier intraday decision, use a prior completed session or the developing values available then. Also check market coverage: native footprint-dependent tools support US equities and crypto, while forex, commodities, and CME futures currently use candle data. US equity volume from Cboe EDGX is exchange-specific, not consolidated volume from every US venue.
Turn Chart Patterns Into Rules You Can Evaluate
Ascending triangles, double bottoms, and cup-and-handle formations describe different price structures. A pattern name alone does not specify an entry, stop, target, time limit, or sample on which to estimate success. There is no universal completion rate that applies unchanged to every timeframe, market, and definition.
For any pattern you study, write down:
- Formation: how many bars and which highs or lows qualify, including when the pattern becomes identifiable.
- Trigger: whether an intrabar break, completed close, or later retest creates the entry.
- Failure: the exact price or condition that ends the trade idea.
- Exit: the target, trailing rule, time limit, and end-of-session treatment.
- Execution: order type, costs, unfilled-order handling, and whether another entry is allowed.
A volume condition or momentum indicator is an optional filter to test, not a guarantee of confirmation. Adding more filters can delay entries and reduce the sample. Preserve losing examples and missed trades when comparing versions instead of selecting only charts where the pattern worked.
Position Sizing: Calculate the Exposure Behind the Stop
Choose a risk budget that fits the account, strategy, and other open exposure. A fixed-fractional risk approach assigns a chosen fraction of equity to planned loss; it is not the same as spending that fraction of the account on an asset. No fixed percentage is appropriate for every trader or setup.
For a hypothetical stock trade, assume an actual entry at $20, a stop at $19.80, and a $100 planned loss budget. Reserve an estimated $10 for round-trip fees. The remaining $90 divided by the $0.20 entry-to-stop distance allows 450 shares, subject to buying power and liquidity.
| Item | Calculation | Illustrative result |
|---|---|---|
| Purchase value | 450 × $20 | $9,000 |
| Loss at the intended stop | 450 × $0.20 + $10 estimated costs | $100 |
| Gross profit at a $20.60 target | 450 × $0.60 | $270 |
| Profit after the assumed costs | $270 − $10 | $260 |
| Adverse execution at $19.50 | 450 × $0.50 + $10 assumed costs | $235 loss |
The cost allowance is an estimate, and actual costs can be higher. A stop is a trigger, not a guaranteed execution price. The SEC’s stop-order bulletin explains that a triggered stop becomes a market order; a stop-limit may instead remain unfilled. Halts, fast moves, and thin liquidity can make actual losses exceed the plan.
For forex, the quantity calculation must include pip value and account currency. Under the specific assumptions of a USD account, EUR/USD, a 0.0001 pip, and a standard lot of 100,000 euros, one standard lot is about $10 per pip. A $100 budget divided by a 10-pip stop and $10 per pip gives one standard lot before costs. That is 100,000 euros of exposure, not a $100 position. Other pairs require their own pip value and any currency conversion.
Planned Reward Is Not Expected Profit
For a long trade, planned reward-to-risk is (target − entry) divided by (entry − stop). For a short, it is (entry − target) divided by (stop − entry). These formulas require the stop and target to be on the appropriate sides of entry.
The stock example has a gross planned reward-to-risk ratio of 3:1. With the assumed costs, its target profit is $260 against a $100 planned loss, or 2.6:1. In a simplified model with only those two outcomes, breakeven requires a win rate of $100 ÷ ($260 + $100), about 27.8%. Partial exits, missed targets, and worse stop execution change that calculation. Moving a target farther away increases the quoted ratio without establishing that it will be reached often enough.
Psychology: Make Deviations Visible
A practical routine is more useful than a promise that confidence will prevent losses. Before the session, decide which setups you will consider, when you will stop taking new trades, and how you will respond to a loss limit or an execution problem. Include realized losses, open-position risk, and costs in the monitoring plan.
A daily loss threshold can trigger a pause, cancellation of new-entry orders, or a predefined exit procedure. Specify which action applies; simply stopping new entries does not close existing positions. Losses can also exceed the threshold before an order executes.
Do not widen a stop on an unchanged position merely to avoid realizing a loss. That increases planned risk. Volatility-based sizing should be considered before entry, or handled through an explicitly evaluated adjustment policy. Taking partial profits, changing size, or adding a time limit also changes the strategy and should be assessed as such.
After a difficult trade, record the reason for the next decision before acting. A short break can help interrupt an impulsive sequence, but it does not repair an unprofitable method. Distinguish a rule violation from a valid trade that lost money; both deserve review for different reasons.
Use Quant for Strategy Research, Then Review Execution Separately
Ask Quant to build a strategy using precise entry, exit, sizing, and session rules. Review the generated code and run it on the intended symbol and timeframe. If converting an indicator, decide how its signals map to orders instead of assuming the indicator already defines a complete trading system.
Set realistic commission, slippage, capital, order size, and margin assumptions. The native backtest viewer lets you inspect performance and individual trades. Check order timing, candles that touch both stop and target, and end-of-session exits. Standard price candles are appropriate for this review; synthetic Heikin Ashi prices do not represent executable market prices.
Reserve a later period before tuning. Compare a limited set of clearly recorded variations, then evaluate the chosen version on that unseen data. Repeatedly adjusting the same history until the chart looks good weakens the evidence. A manual historical review or paper-trading exercise can reveal mistakes, but neither reproduces all live fills and constraints.
AI-generated code, an alert, and a broker order are distinct. Quant does not automatically prove profitability, continuously optimize a live account, or enforce broker risk limits. LuxAlgo’s documented Strategy Alerts are part of the legacy Assistant and TradingView toolkit workflow, separate from Quant. Any execution system needs its own tested handling of rejected orders, partial fills, duplicate signals, and connection failures.
Watch: A Technical Analysis Course
Close the Loop With a Trading Journal
Open the LuxAlgo Journal beside the native charts to review recorded trades. It supports manual accounts, statement imports, and supported broker connections. Fills are grouped into round trips with average entry and exit, fees, net profit or loss, and duration. The Journal belongs to your account, so changing workspaces keeps the same records.
Keep the planned setup and exit conditions alongside the actual executions. Use consistent tags and notes to distinguish the strategy, session, and any unplanned change. Compare similar trades, including losses, rather than judging the method from a single strong day.
- Before trading: confirm the market, session, setup rules, available capital, and risk limits.
- During trading: monitor orders and positions against the plan, including execution problems.
- After trading: reconcile fills and costs, record deviations, and identify one specific question for the next review.
The next step is to evaluate one clearly defined approach from start to finish. Keep its assumptions visible, test it on data it was not tuned to, and use actual records to see where analysis and execution differ.
Read next