Fundamental Investing 101: Key Concepts
Fundamental investing evaluates a business to estimate what its shares may be worth. Investors examine financial statements, competitive position, management decisions, and economic conditions, then compare a valuation range with the market price. The result is an estimate built on assumptions—not a discovery of an unchanging “true value.”
A useful analysis answers three questions: How does this company generate cash? What could change that cash generation? What price leaves sufficient room for the risks and uncertainty? Financial ratios can help, but they need to be connected to the business behind the numbers.
Fundamental and Technical Analysis
| Aspect | Fundamental analysis | Technical analysis |
|---|---|---|
| Main question | What might the business and its shares be worth? | What does market activity reveal about price structure and trading conditions? |
| Inputs | Accounts, business economics, competition, and financial assumptions. | Price history, volume, and defined indicators or patterns. |
| Typical output | A business thesis, scenarios, and valuation estimates. | A description of trends or a testable entry and exit rule. |
| Limitation | Forecasts and valuation assumptions can be wrong. | Historical patterns do not guarantee future outcomes. |
These methods are not confined to exclusive time horizons. Fundamental news can matter immediately, while technical analysis can use weekly or monthly data. Combining them is useful only when each contributes a clear, separately understood role.
Investing Basics: Fundamental Analysis
This Charles Schwab lesson introduces financial statements and fundamental research. Use it alongside the worked examples below to connect the terminology with an actual analysis process.
Reading Financial Statements
Main Financial Reports
The SEC’s financial-statement guide identifies four main statements. Read them together with the notes, accounting policies, auditor’s report where applicable, and management’s discussion and analysis, often abbreviated MD&A.
| Statement | Time basis | What to investigate |
|---|---|---|
| Income statement | A reporting period | Revenue, expenses, margins, and earnings; distinguish recurring results from unusual items. |
| Balance sheet | A point in time | Assets, liabilities, and shareholders’ equity, including funding obligations. |
| Cash-flow statement | A reporting period | Cash from operating, investing, and financing activities. |
| Statement of shareholders’ equity | A reporting period | Changes from earnings, distributions, share transactions, and other equity items. |
Accounting profit is not the same as cash received. A sale on credit can increase revenue before the customer pays. Capital expenditure uses cash but is generally reflected in earnings over time through depreciation rather than entirely when paid. These differences are reasons to reconcile the statements, not automatically signs of poor reporting.
The balance-sheet relationship is assets = liabilities + shareholders’ equity. The notes help explain what those amounts contain, including estimates and obligations that a headline total can hide. Read management’s explanation critically and compare it with the underlying figures.
Key Financial Ratios
Use consistent definitions and reporting periods when comparing companies. The following common formulas describe different parts of performance; none supplies a universal pass or fail score.
| Measure | Common calculation | Interpretation check |
|---|---|---|
| Operating margin | Operating income ÷ revenue | Compare similar business models and investigate changes in costs or product mix. |
| Net profit margin | Net income ÷ revenue | Interest, taxes, and unusual items can change the result. |
| Return on equity | Income attributable to common shareholders ÷ average common equity | Leverage or a small equity balance can inflate the figure; negative equity complicates interpretation. |
| Quick ratio | (Cash + short-term investments + receivables) ÷ current liabilities | Collection quality and the business’s cash cycle matter, as do the obligations coming due. |
| Debt-to-capital | Interest-bearing debt ÷ (debt + equity) | Specify book or market values consistently and examine maturity dates and borrowing terms. |
A quick ratio below 1 can prompt further investigation, but it is not automatically a liquidity crisis. A debt-to-capital figure above 40% is not a universal danger threshold. A utility, retailer, software company, and bank have different financial structures; compare the measure with relevant peers and the company’s own history.
Statement Analysis Steps
- Understand the business: Identify the products, customers, revenue model, and major operating costs.
- Check the evidence: Record the reporting date, accounting basis, auditor’s opinion, and any restatements or unusual adjustments.
- Compare periods: Examine revenue, margins, cash generation, debt, and share count over time.
- Explain the changes: Separate organic growth from acquisitions, currency movements, and one-off effects.
- Build scenarios: Translate the explanation into assumptions that can later be checked.
For example, revenue rising from $100 million to $110 million is 10% growth. If operating margin falls from 20% to 15%, operating profit falls from $20 million to $16.5 million—a 17.5% decline. Looking only at the sales headline would miss the deterioration in profitability.
Company Valuation Methods
Basic Valuation Metrics
Price-to-earnings, or P/E, compares share price with earnings per share. A $50 share price and $2.50 of annual EPS produce a multiple of 20. If sustainable EPS is only $1.25, the same price represents 40 times earnings. Specify whether the denominator uses reported past earnings, adjusted earnings, or a forecast.
A low multiple can reflect a bargain, weak prospects, or temporarily high cyclical profits. Negative earnings generally make the usual P/E comparison unhelpful. Compare businesses with similar economics and account for differences in growth, leverage, and earnings quality rather than treating the broad market’s multiple as a universal target.
Price-to-book, or P/B, compares market price with accounting equity per share. Suppose a company has $100 million of assets, $75 million of liabilities, and 10 million shares outstanding. Book equity is $25 million, or $2.50 per share. At a $5 share price, P/B is 2.0.
Book value is not necessarily liquidation value or the value of the operating business. Asset quality, accounting treatment of intangible investment, and future profitability all matter. A P/B below 1 therefore does not establish that shares are undervalued.
Discounted Cash Flow: Match the Model to the Cash
Discounted cash flow, or DCF, estimates present value from expected future cash flows. A forecast needs assumptions about revenue, margins, taxes, reinvestment, working capital, and the cash left after supporting the business. Growth without the investment needed to achieve it can exaggerate value.
Aswath Damodaran’s NYU valuation framework distinguishes cash flows to the firm from cash flows to equity. Firm cash flows are discounted at the weighted average cost of capital, or WACC; equity cash flows use the cost of equity. Mixing these approaches produces an inconsistent valuation.
Keep the currency and inflation treatment consistent too. Nominal cash flows need a nominal discount rate. After valuing operations, adjust for non-operating assets, debt, and other relevant claims to reach common equity value, then use an appropriate share count. Do not count the same cash twice.
A Worked Valuation and Sensitivity Example
Consider a hypothetical mature business with next year’s free cash flow to the firm of $10 million, growing at 2% every year thereafter. In this simplified steady-growth model:
Operating value = next year’s firm cash flow ÷ (WACC − growth).
Assume $10 million of additional non-operating cash, $30 million of debt, no other claims, and 10 million shares. Changing only the discount-rate assumption changes the estimated value substantially:
| Assumption or result | 8% WACC | 10% WACC |
|---|---|---|
| Next year’s cash flow / perpetual growth | $10 million / 2% | $10 million / 2% |
| Operating value | $166.67 million | $125.00 million |
| Equity value after cash and debt adjustments | $146.67 million | $105.00 million |
| Estimated value per share | $14.67 | $10.50 |
At a $12 market price, the shares appear below the first estimate and above the second. The arithmetic is precise, but the assumptions are uncertain. The model also assumes the business can sustain the specified cash-flow growth indefinitely, with a discount rate greater than growth.
A fuller model may forecast several years separately before estimating a terminal value. Test changes in cash generation and growth as well as the discount rate. A margin of safety—a price below a cautiously estimated value—can allow room for error, but cannot make an incorrect thesis safe.
Non-Financial Analysis
Leadership Evaluation
Evaluate decisions that can be checked: how management allocated capital, financed acquisitions, treated shareholders, responded to problems, and delivered against earlier commitments. Compensation incentives and related-party transactions can reveal whether management’s interests align with outside investors.
Employee turnover, customer complaints, and operational disruptions can suggest questions worth investigating. They do not automatically establish the cause of a financial outcome. Compare several sources and distinguish a documented pattern from an isolated anecdote.
Market Position Strength
A competitive advantage must have an economic consequence. Lower costs may support margins; switching costs may support retention; a differentiated product may support pricing. Ask what prevents competitors from copying the advantage and what the company must spend to maintain it.
Customer concentration, supplier dependence, patent expiry, regulation, and changing technology can weaken an apparently strong position. Translate those risks into revenue, cost, or reinvestment scenarios rather than giving the company a favorable label without changing the model.
Market and Industry Review
Study competitors, substitutes, distribution channels, and the direction of customer demand. A growing industry can still produce poor shareholder returns if competition consumes the profits or firms repeatedly issue new shares to fund expansion.
Environmental, workforce, and governance issues can be financially material when they affect liabilities, operations, access to customers, or financing. Assess those connections directly. A broad score or survey percentage does not prove that a company will outperform.
Economic Impact Factors
Economic Measures
GDP, employment, inflation, and interest rates help frame scenarios. Connect them to the business: weaker demand can affect sales, wage or input inflation can pressure margins, and higher borrowing costs can affect refinancing. The impact depends on pricing power, contract terms, and the balance sheet.
The Federal Reserve’s 2% longer-run inflation objective refers to the PCE price index. It is neither a promise about actual inflation nor the return an investor needs for every goal. For example, an 8% nominal return with 3% inflation gives approximately 4.85% after inflation, calculated as 1.08 ÷ 1.03 − 1, before taxes.
Business Cycles and Market Timing
Early expansion, mature expansion, slowing growth, and recession are useful descriptions, but they are not a calendar with fixed durations or guaranteed stock returns. Markets react to expectations, while economic data arrive with delays and revisions.
The NBER dates U.S. business-cycle turning points retrospectively, waiting for sufficient evidence. Knowing the eventual label for a past period is different from having a usable signal at the time. Avoid building a strategy that assumes future revisions or later cycle classifications were already known.
Global Market Effects
Map exposure to overseas customers, suppliers, production sites, currencies, trade restrictions, and political risks. A supply disruption may increase costs for one company while benefiting a competitor; the effect is not a fixed percentage for every business.
Use plausible scenarios and identify the evidence that would make each more likely. Consider whether a company can change suppliers, pass through costs, or fund a prolonged disruption. Those responses belong in the valuation assumptions and risk review.
Creating an Investment Plan
Investment Decision Process
Create a short investment memo containing the business explanation, source documents, key financial trends, valuation range, principal risks, and reasons the market might disagree. Record which assumptions matter most and what evidence would invalidate them.
Keep company, industry, and economic analysis connected. If a forecast requires stronger demand, explain why; if it assumes better margins, identify the operational change that supports them. A model should make the reasoning visible rather than hide it behind a single target price.
Organizing Research with LuxAlgo
Use LuxAlgo’s charting platform to review supported symbols and organize market observations. Open Panels → Watchlist, choose Add symbol, and select a row to load its chart. The Watchlist provides a convenient research list; it does not replace the issuer’s financial filings or your valuation assumptions.
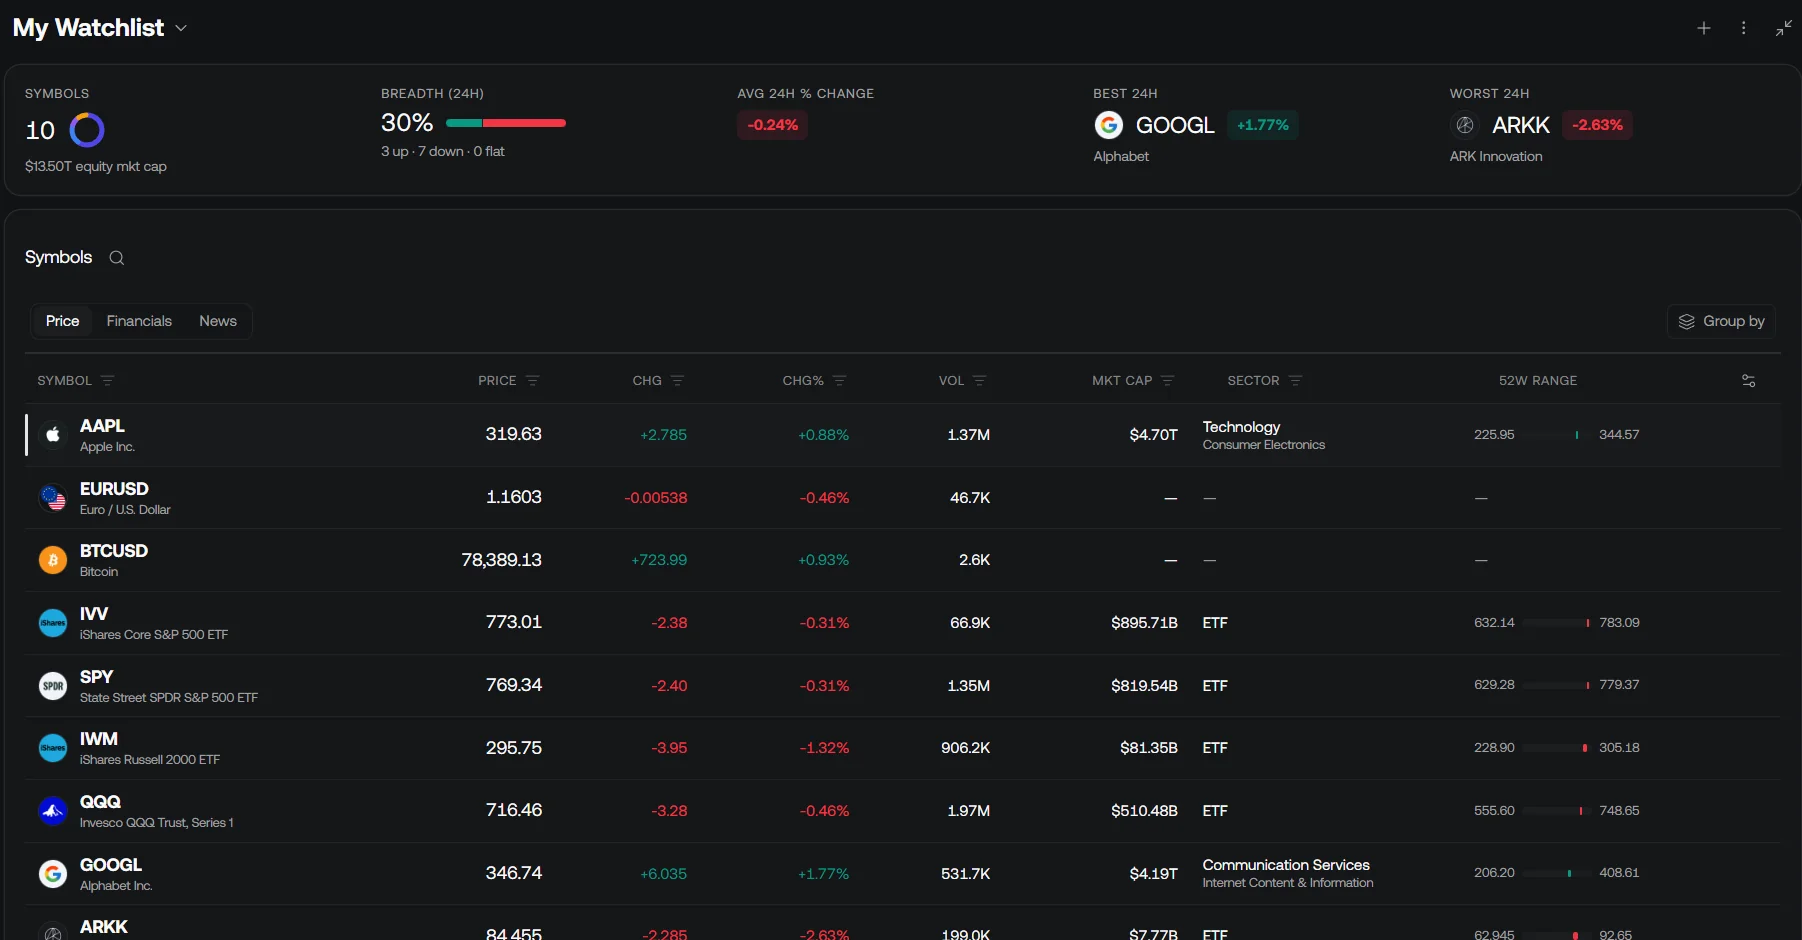
Confirm the exact instrument and data source before interpreting a chart. If you want to test a separate price-based rule, Quant, our coding agent, can help create the strategy. Review the code, run it, and inspect its assumptions and trades. That process does not automatically build a DCF or establish that historical financial information was available on each test date.
Use the LuxAlgo Journal to record trades through manual entry, import, or supported broker connections, and keep notes on the thesis and subsequent review. Separate changes in the business from changes in the share price so that a losing trade does not silently become a different investment thesis.
Risk Control Methods
Choose exposure in light of the uncertainty, liquidity, concentration, and potential loss. A valuation discount alone does not justify a large position. Several companies may share the same economic risk even when their names and sectors differ.
Diversification can reduce exposure to an individual business, but cannot eliminate broad market losses. Review the thesis when new filings, financing decisions, management changes, or competitive developments alter the evidence. Also review whether the position still fits your time horizon and financial needs.
Next Steps
- Read the statements, notes, and management discussion for one business you can explain.
- Calculate a small set of relevant measures using consistent definitions and periods.
- Build a valuation range with explicit assumptions and downside scenarios.
- Connect management, competition, and economic risks to that model.
- Record the decision, position constraints, and evidence that would trigger a reassessment.
Fundamental investing is an ongoing comparison between evidence, assumptions, and price. The aim is a defensible decision that can be revised when facts change, rather than confidence in a target price simply because a spreadsheet produced it.
Read next