John A Paulson Crisis Playbook Key Takeaways
John A. Paulson’s crisis trade illustrates the value of investigating mispriced risk and choosing an instrument that expresses the thesis. His bet against subprime mortgage credit became famous during the 2007–2008 financial crisis. The useful lesson is a research and risk-management process, not a promise that investors can reliably predict the next crash.
This guide distinguishes Paulson’s historical credit trade from general crisis indicators and educational trading examples. LuxAlgo charts and Quant can help investigate price-based rules and market context; they do not reproduce an institutional mortgage-credit portfolio or guarantee downside protection.
- Research the underlying exposure: examine cash flows, debt quality, leverage, and the price paid for risk.
- Plan for being early or wrong: account for ongoing costs, adverse moves, and the ability to remain in a position.
- Separate signals from forecasts: economic and technical measures inform scenarios rather than identify a certain crash date.
- Prepare for recovery: reassess valuation and financial strength instead of buying solely because an asset has fallen.
What Paulson’s Crisis Trade Actually Shows
Paulson used credit-default swaps to take bearish exposure to mortgage securities as housing and credit conditions deteriorated. Wiley’s account of the trade describes approximately $15 billion generated for him and his investors in 2007. That historical result is distinct from personal compensation, assets under management, or the profit from one transaction.
A contemporaneous December 2007 report put the average gain across Paulson’s Credit Opportunities funds at 340% in that year’s first nine months.
Those exceptional outcomes do not establish that an ordinary investor could obtain the same contracts, financing, information, or execution. They also do not validate every later investment. Evaluate the thesis, instrument, and risks together rather than treating a manager’s most successful trade as a universal playbook.
How to Spot Market Crisis Signals
Reading Economic Warning Signs
Use a small set of clearly defined economic indicators to organize research. The measures below are general tools, not a verified list of indicators Paulson used. Their timing and limitations matter as much as their readings.
| Indicator | What to examine | What it cannot establish |
|---|---|---|
| Yield curve | The spread between the 10-year Treasury yield and the 3-month Treasury rate. A negative spread is an inversion. | An inversion is not an 80% threshold or a certain stock-market crash date. |
| Labor market | Changes in unemployment and the real-time Sahm Rule measure. | A deterioration signal is not a precise advance trading entry. |
| Credit conditions | Spreads, lending standards, delinquencies, and refinancing requirements. | A broad spread change alone does not identify which security is mispriced. |
| Cross-asset behavior | Relative performance of bonds, equities, and sector funds over consistent dates. | The relative-price measure can rise for several reasons and does not independently prove a flight to safety. |
The New York Fed’s yield-curve model uses the 10-year minus 3-month spread to estimate recession probability twelve months ahead. The probability is a model output, not the percentage of the curve that is inverted. It should be evaluated alongside other evidence rather than converted directly into a short-selling instruction.
The Sahm Rule recession indicator compares the three-month average unemployment rate with its lowest three-month average during the preceding twelve months. A rise of at least 0.50 percentage points is its signal. For example, 4.1% versus 3.5% gives 0.6 percentage points. This differs from unemployment simply crossing a two-year average.
Indicators can misfire. A May 2025 St. Louis Fed discussion examines how recession-probability measures differ and the Sahm Rule’s 2024 readings. Record the data available at each historical decision date, including release delays and later revisions, when evaluating a signal.
Treat Custom Ratios as Hypotheses
The “blood indicator” sometimes defined by dividing the 3-month Treasury rate by a high-yield spread, compared with a 100-week average, is not established here as Paulson’s method. Before testing this relationship, identify the exact series, units, sampling frequency, and direction of the proposed signal. A small denominator can create a large ratio without a new crisis.
Likewise, TLT/XLE compares two very different exposures. TLT holds long-duration U.S. Treasury exposure, while XLE represents an energy-equity sector index. A rising ratio may reflect bond gains, energy-stock losses, or both. Interest rates, inflation, oil prices, and distributions can complicate interpretation; use consistent adjusted data and inspect both components.
Going Against Market Consensus
A contrarian position needs evidence that consensus expectations are wrong and that the proposed payoff compensates for the risks. Write down what the market appears to assume, what your analysis suggests instead, and what would invalidate the difference. Being unpopular is not evidence of being correct.
For mortgage credit, this means examining underwriting, borrower capacity, delinquencies, collateral, and the structure of losses across securities. For a company, it means financial statements and refinancing needs. A price chart can complement that work but cannot replace analysis of the contractual cash flows.
Market Analysis with LuxAlgo
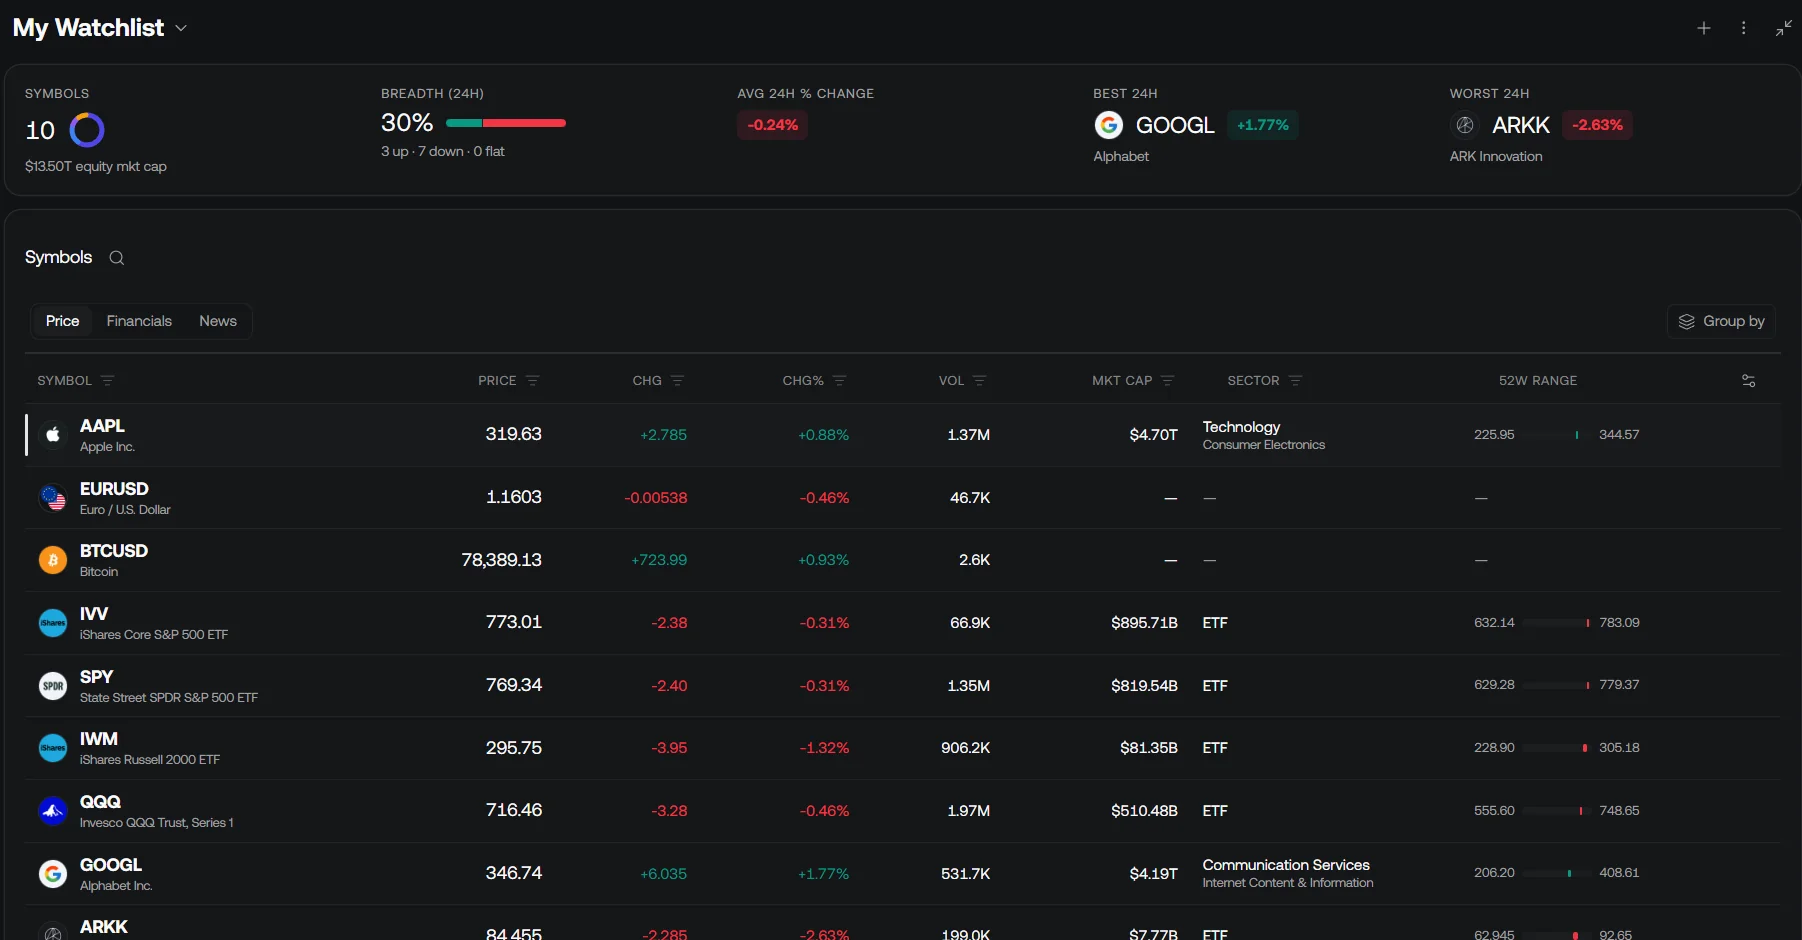
Organize supported instruments in a LuxAlgo watchlist and compare them in a multi-chart workspace. Look at trend changes, volatility, and price-volume relationships over consistent dates. Identify the data source: U.S. equity data on LuxAlgo charts uses EDGX, not a consolidated feed.
Volume profiles describe executed volume at price, while volume delta describes the balance of classified buying and selling activity in the available data. They cannot identify a particular institution or prove that informed investors are returning. A market-structure break, divergence, or trend-exhaustion reading is a condition to test, not confirmation of a recession.
Short-Selling During Market Crashes
Using Credit-Default Swaps
A CDS protection buyer pays contractual premiums and may receive compensation when specified credit events or losses occur. The exposure can gain market value as credit conditions worsen, but its terms, counterparty, collateral requirements, and liquidity determine the actual risk. It is different from borrowing and selling shares or purchasing a stock put.
The Reserve Bank of Australia’s ABX explanation describes indices referencing CDS on subprime residential mortgage-backed securities; the first series began trading in January 2006 and referenced 20 RMBS transactions. These were mortgage-credit benchmarks, not an ordinary stock index or a direct purchase of houses.
BIS research on ABX pricing finds that risk appetite and market liquidity contributed to price declines alongside credit concerns. A fall in the index therefore should not be interpreted as a pure estimate of future mortgage defaults. Distinguish the underlying credit thesis from the price and financing of the instrument used to express it.
Trade Entry and Cash Management
The cost of waiting can defeat an otherwise plausible thesis. In a simplified hypothetical, $1 million of CDS notional with a 2% annual premium costs $20,000 per year before other terms or upfront payments. Two years without an offsetting gain consumes $40,000. Real contracts require a more complete cash-flow and collateral analysis; notional is not the amount of cash invested or a complete loss measure.
For conventional stock shorting, the SEC’s Regulation SHO overview explains the possibility of unlimited loss as the share price rises. Borrow availability, fees, dividends owed, margin requirements, and recalls also matter. A correct bearish view does not guarantee a profitable short position or the ability to hold it.
Define and Backtest a Short Rule with Quant
Use Quant, our coding agent, to prototype a clearly specified price-based hypothesis. For example, investigate a short entry after a completed daily close falls below the lowest low of the preceding 20 bars, excluding the current bar. Specify the next execution opportunity, permitted trading dates, sizing, a stop, and an exit rule before testing.
Review the generated code in Code Review before running it while signed in. Use standard price candles and explicit commission, slippage, and margin settings. Check whether the simulation accounts for borrow costs and availability; if it does not, model those separately rather than assuming a historical short was executable.
The backtest viewer provides Performance, Trades Analysis, and Trades Log views. Inspect long/short results, individual fills, drawdown, and the number of trades. Compare later periods and stress costs. This is your educational strategy, not a recreation of Paulson’s mortgage-credit trade.
Crisis Risk-Control Methods
Trade Size and Portfolio Balance
Set risk limits from account equity, instrument behavior, liquidity, and the rest of the portfolio. There is no verified universal Paulson rule here of 2.5% per position, 10–12% for high conviction, or a 25–30% reduction whenever volatility increases. Distinguish allocation, planned loss, and potential realized loss.
Suppose a $50,000 account assigns an illustrative $250 planned-loss budget to a stock short entered at $50 with a buy-stop at $55. Before costs, $250 ÷ $5 allows 50 shares. If the exit instead fills at $60 after a gap, the loss is $500. Widening the stop to $60 while retaining the same planned budget would reduce the initial size to 25 shares; widening a stop without resizing increases planned risk.
Maintain liquidity for ordinary obligations and adverse scenarios. Cash reserves provide flexibility but have an opportunity cost and do not automatically offset losses elsewhere. Stress correlated positions together: three $10,000 exposures each losing 20% produce a combined $6,000 loss, even if the companies have different names.
Market-Sector Links and Trade Crowding
Review common dependencies such as credit access, interest rates, energy prices, and customer demand. Correlations can change abruptly, and a crowded position can become expensive to exit when many traders act at once. For merger arbitrage, examine financing conditions, regulatory approvals, termination rights, and the loss if the deal fails instead of focusing only on the quoted spread.
Track gross exposure, net exposure, available liquidity, and concentration separately. Profits, fund returns, and assets under management answer different questions; a rise in managed assets can include investor flows and is not proof of a particular risk-control method’s effectiveness.
Risk Review in LuxAlgo
Use chart drawings to make the planned entry, invalidation point, and target visible. Compare the actual strategy settings with that plan, and save runs so the tested symbol, timeframe, inputs, and assumptions remain identifiable. An attractive risk/reward drawing does not account for every fill or funding risk.
Review recorded trades in the LuxAlgo Journal and reconcile them with broker records. Notes should identify the thesis, expected catalyst, costs, and reason for exiting. Separate chart simulations do not create a portfolio stress test with shared capital; assess joint losses and financing outside a single-symbol run.

Buying During Market Recovery
Finding Oversold Assets
A large decline can create an opportunity or reveal permanent impairment. Check whether a business can finance itself, whether debt holders rank ahead of shareholders, and whether new capital could dilute existing equity. Compare a conservative valuation with the current price and define what would disprove the recovery thesis.
Avoid confusing a segment’s growth with overall profitability. For a historical example, Thryv’s full-year 2023 results, released February 22, 2024, reported SaaS revenue of $263.7 million, up 21.9%, while Marketing Services revenue fell 33.8% to $653.2 million. Consolidated net loss was $259.3 million, including a $268.8 million goodwill impairment. SaaS adjusted EBITDA of $12.0 million was not SaaS net income.
Those figures illustrate why revenue, adjusted earnings, and consolidated profit must be distinguished. They do not establish Paulson’s private investment rationale or constitute a current recommendation to buy the stock. Read the latest filings before making a present-day valuation judgment.
Market-Sector Rotation Strategy
Economic phases are a useful organizing framework, not a fixed schedule of winning sectors or a verified Paulson allocation table. Stocks can anticipate an economic recovery before backward-looking data improve. Inflation, policy, balance sheets, and starting valuations can produce different sector outcomes in different cycles.
| Research scenario | Candidate exposures to investigate | Key question |
|---|---|---|
| Demand begins to stabilize | Industrials, transports, and other cyclical businesses | Are orders and financing improving enough to support the valuation? |
| Investment spending strengthens | Technology, industrials, and materials | Is earnings growth broad, sustainable, and already priced in? |
| Inflation or commodity constraints persist | Energy and materials alongside interest-rate-sensitive assets | Does the price reflect a temporary supply shock or a durable cash-flow change? |
| Activity weakens again | Staples, utilities, and other defensive candidates | Does balance-sheet or interest-rate risk offset defensive demand? |
Compare supported sector instruments with a broad-market baseline on LuxAlgo charts. If you test rotation, define the ranking method, review frequency, entry timing, costs, and treatment of cash. A set of independent winning chart tests does not establish a portfolio that could hold only one selected sector at a time. Avoid using later-known recovery dates to choose historical trades.
Trading Psychology in Crisis Markets
Avoiding Panic Selling and FOMO
A written decision process is more useful than a promise to stay calm. Before entering, record why the position exists, its size, the evidence that would invalidate it, and the actions permitted after a loss. Revisit the plan when facts change; discipline does not mean retaining a broken thesis indefinitely.
- Panic: distinguish a price move from new information, while honoring predetermined risk limits.
- Fear of loss: reduce exposure to a tolerable level instead of moving the invalidation point solely to avoid recognizing a loss.
- FOMO: require the same research and sizing checks after a rapid rally as before it.
- Overconfidence: review failed ideas and execution errors, not just successful trades.
Follow Evidence and Configure Monitoring Carefully
Read filings, earnings releases, and primary economic data with their publication dates. Set a review schedule and a small number of meaningful conditions that warrant attention. A notification should prompt a defined check, not an emotional decision or an assumption that a trade is safe.
Do not assume a saved Quant script automatically becomes an alert. Verify the supported workflow and delivery behavior in the product you use.
For any email or webhook setup, test the symbol, timeframe, condition, and resulting message before relying on it. Notifications can be delayed or fail, and a webhook is not confirmation of a broker fill. Keep execution controls and account monitoring separate from signal generation.
John Paulson Tells the Story of Wall Street’s Greatest Trade
This Bloomberg Wealth interview with David Rubenstein was published August 31, 2021. It offers Paulson’s retrospective account of the mortgage-market trade. Treat the historical discussion as context for research and instrument selection, not a forecast of the next crisis.
Main Points from Paulson’s Methods
Study the exposure beneath the price, distinguish a thesis from an executable trade, and plan for adverse outcomes before sizing a position. Crisis investing also requires enough liquidity and flexibility to respond when the evidence changes. Historical success does not eliminate the chance of substantial losses.
Start your own research with a supported instrument on LuxAlgo charts, use Quant to implement a specific rule, and inspect the resulting trades. Keep fundamental analysis, portfolio stress scenarios, and broker constraints alongside the chart work. Move from research to paper evaluation before considering any controlled live use.
FAQs
How can I use John A. Paulson's crisis investment strategies to protect and grow my portfolio during market downturns?
Apply the general principles of detailed research, liquidity planning, position limits, and testing adverse outcomes. Separate the investment thesis from the instrument used to express it. These practices can improve decision-making, but they do not guarantee capital protection or gains during a crisis.
How did John Paulson predict the 2008 financial crisis, and how can I apply his strategies today?
Paulson identified vulnerabilities in mortgage credit and used credit-default swaps to take bearish exposure before the crisis fully unfolded. Study credit quality, leverage, valuation, and contract terms rather than assuming a chart indicator can recreate the trade. Economic signals have uncertain timing and can be wrong.
How can LuxAlgo's tools help apply John A. Paulson's strategies for spotting market shifts and managing risks effectively?
LuxAlgo watchlists and charts help organize market observations, while Quant can help code a defined research hypothesis. Review code, inspect backtest trades and costs, and compare recorded outcomes in the Journal. These tools support your research; they do not reproduce Paulson’s institutional CDS positions or guarantee a crisis forecast.
References
- Wiley: John Paulson, The Greatest Trade of All Time
- New York Fed: yield curve as a leading indicator
- FRED: Sahm Rule recession indicator
- RBA: ABX.HE credit-default-swap indices
- BIS: pricing subprime mortgage risk
- SEC: short selling and Regulation SHO
- Thryv: full-year 2023 financial results
- LuxAlgo: creating strategies with Quant
- LuxAlgo: backtest viewer and simulation settings
- LuxAlgo: Journal
Read next