Market Fundamentals: Float & Shares Explained
Shares outstanding measure ownership currently held by shareholders; float estimates the portion available for public trading under a stated methodology. Neither number tells you how many shares are offered for sale at the current price. For trading, combine the ownership data with spreads, volume, news and the ability to enter or exit a position.
- Outstanding shares: include public, insider and other shareholder holdings, but exclude shares held in treasury by the company.
- Float: excludes holdings treated as unavailable or strategic by the data provider. Definitions and update dates matter.
- Turnover: trading volume divided by float measures activity relative to a share estimate, not unique owners or buying pressure.
- Risk: a small float can amplify price sensitivity, but a large float does not guarantee liquidity or protect an investment from losses.
Float vs. Outstanding Shares
Understanding the Share Categories
Stock represents an ownership interest. Common stock often has voting rights; preferred stock typically has priority over common stock for dividends and liquidation proceeds, subject to its terms. Voting rights, conversion rights and payment features vary by class. Do not combine different classes mechanically when comparing share counts or values.
| Term | What it describes | Common mistake |
|---|---|---|
| Authorized shares | Shares the company is permitted to issue under its governing documents | Treating authorization as shares already sold |
| Issued shares | Shares issued by the company; may include repurchased treasury shares that have not been retired | Equating all issued shares with outstanding shares |
| Outstanding shares | Issued shares held by shareholders, excluding treasury shares | Assuming all are freely tradable |
| Float shares | The estimated tradable subset using a provider’s exclusions | Confusing the estimate with immediate order-book supply |
| Diluted share measure | A measure reflecting potential shares under the applicable calculation | Treating options or convertibles as already-issued float |
A point-in-time share count also differs from the weighted-average shares used for earnings per share. Read the date, class and units beside the number. A financial statement can legitimately show several different share figures because they answer different questions.
How to Calculate Float
A simplified calculation is:
Float shares = outstanding shares − holdings excluded under the chosen methodology.
Do not subtract the same holding twice because it is both an insider stake and subject to a restriction. Treasury shares have already been excluded from outstanding shares. Nor should every institutional holding automatically be removed: a portfolio investment and a strategic controlling stake are not equivalent.
S&P Dow Jones Indices’ float methodology sets detailed ownership exclusions and adjustment rules. A commercial data provider’s float estimate may differ from an index provider’s investable weight factor. Treat the methodology as part of the data rather than assuming a universal list of excluded shareholders.
Consider a fictional company with 500 million authorized shares, 470 million issued shares and 20 million treasury shares. Outstanding shares are 450 million. If 150 million outstanding shares are excluded as strategic or restricted holdings under the assumed method, float is 300 million. The float percentage is 300 ÷ 450, or about 66.7%.
Float and Market Capitalization
At an assumed $10 per share, that single share class has $4.5 billion of total market capitalization and $3 billion of float-adjusted market capitalization. The price, share class and measurement date must be consistent. For multiple classes, company-level equity value may require valuing each class separately.
The S&P 500 uses float-adjusted market-cap weighting. That does not mean all indexes use float, or that float determines price. An index weight also depends on other constituents and the index’s calculation and maintenance rules.
Watch the units in filings: “public float” can refer to a dollar market value of equity held by non-affiliates rather than a share count. A market-value figure and a trading-data float count cannot be substituted for one another without checking what was measured.
How Float Relates to Trading
Liquidity and Price Stability
A smaller tradable supply can make price more sensitive to a sudden change in demand or available sellers. But liquidity depends on participation, spread, displayed and undisplayed interest, news and market conditions. A high-float stock can gap sharply, while an inactive stock can trade poorly despite a seemingly substantial float.
There is no universal boundary at 20 million or 100 million shares that separates risky stocks from safe ones. A stock with 10 million float shares priced at $1 has very different dollar exposure from one with the same share count priced at $100. Float percentage, market value and actual trading conditions add context.
A $10.00 bid and $10.10 ask produce a $0.10 spread, or about 1% of the $10.05 midpoint. Buying 1,000 shares at the ask and immediately selling at the unchanged bid loses $100 before fees. Float alone cannot tell you whether that spread or enough executable size will be available.
Float Turnover: What the Ratio Means
Session float turnover = session share volume ÷ estimated float shares. Traders also call this float rotation. Match the numerator and denominator: share volume is not dollar volume, and regular-session volume is not the same as an extended-hours total.
If 30 million shares trade during a session and the estimated float is 10 million, turnover is 3.0×. That does not establish that every floating share traded three times—or even once. Some shares can trade repeatedly while others never move. The ratio summarizes aggregate transactions relative to an estimate.
Every executed trade has a buyer and a seller. High turnover does not, by itself, identify aggressive buying, net accumulation or the direction of the next move. Examine price response, the catalyst and execution conditions. The same high turnover can appear during a rally, a selloff or a volatile round trip.
Data coverage is crucial. Comparing one venue’s volume with a company-wide float produces a different metric from consolidated share volume divided by that float. Keep sessions, venue coverage and corporate-action adjustments consistent before comparing stocks or dates.
Corporate Actions and Float Changes
| Event | Possible share-count effect | What to verify |
|---|---|---|
| Completed repurchase | Can reduce outstanding shares and the public float | Actual purchases, source of shares, offsetting issuance and dates |
| New-share issuance | Increases outstanding shares; float depends on restrictions and ownership | Number issued, proceeds, share class and availability for trading |
| Sale by an existing shareholder | Does not itself create new outstanding shares; may increase float | Whether a previously excluded holding becomes publicly tradable |
| Lockup expiry | May make existing shares eligible for sale | Contract terms, other restrictions and actual sales |
| Stock split or reverse split | Changes shares and per-share price mechanically | Adjustment factor and consistent historical data |
A repurchase authorization is permission to buy, not proof that shares have been purchased. Similarly, a lockup ending is not proof that every eligible holder immediately sells. Check company filings and subsequent disclosures instead of inferring a completed supply change from a headline.
New shares can dilute an existing owner’s percentage, but the company also receives proceeds when it sells shares for cash. Price effects depend on terms, expectations and use of funds. A secondary transaction by an existing holder has different mechanics from primary issuance; offerings can contain both.
A two-for-one split would turn the fictional company’s 450 million outstanding and 300 million float shares into 900 million and 600 million, with an illustrative $10 price adjusting to $5. Market value is unchanged by the split alone. It has not created new economic ownership just because the share count doubled.
Video: Outstanding Shares vs. Share Float
This Investing with Christy Su lesson introduces the distinction between outstanding shares and float. Use it alongside the share-category and methodology distinctions above, and check current filings rather than treating the examples as live company data.
Short Interest and Other Float Metrics
Short Interest vs. Trading Volume
FINRA distinguishes short interest from short-sale volume. Short interest measures open short positions at a reporting snapshot; daily short-sale volume counts transactions classified as short sales within the data’s coverage. A position opened and closed the same day can contribute to volume without remaining in the short-interest snapshot.
Short interest as a percentage of float = reported short shares ÷ float shares × 100. If reported short interest is 2 million and float is 10 million, the ratio is 20%. Check the reporting date, publication lag and float date. It is not a real-time reading of all market participants’ views, and 20% is not a universal squeeze trigger.
Short interest can exceed the float because shares sold short can subsequently be lent and sold short again. The lending mechanics are discussed in SIFMA’s comment letter to FINRA. That ratio alone does not establish unlawful trading or predict a squeeze. Borrow availability, fees, recalls and market demand still matter.
Days to cover divides short interest by average daily share volume. Two million shares short divided by 500,000 average daily shares gives four days. It is a scale comparison, not a deadline by which shorts must buy back shares. Actual volume and participation can change abruptly.
Float Is Context, Not Price Control
A concentrated float can make a stock more vulnerable to sharp moves or manipulative promotion, but the number is not evidence of manipulation by itself. Large floats do not eliminate fraud, fundamental risk or market-wide selling. Evaluate the issuer, disclosures, trading activity and sources of promotional claims separately.
Using Float Data in a Trading Workflow
Verify the Data Before the Setup
- Identify the class and date. Confirm what the quoted shares represent.
- Compare sources. Reconcile vendor estimates with filings, ownership changes and recent corporate actions.
- Check liquidity directly. Review spreads, volume coverage and executable size.
- Define a hypothesis. Treat turnover, price action and catalysts as inputs to test, not automatic entries.
- Plan execution risk. Consider gaps, halts, slippage and short-borrow constraints.
For example, a planned $100 risk budget and $0.50 distance to an intended exit imply 200 shares before costs. If a gap makes the actual loss $2 per share, the loss is $400. A small float can make execution especially difficult, so a planned stop distance is not a guaranteed loss ceiling.
Research with LuxAlgo Charts and Quant
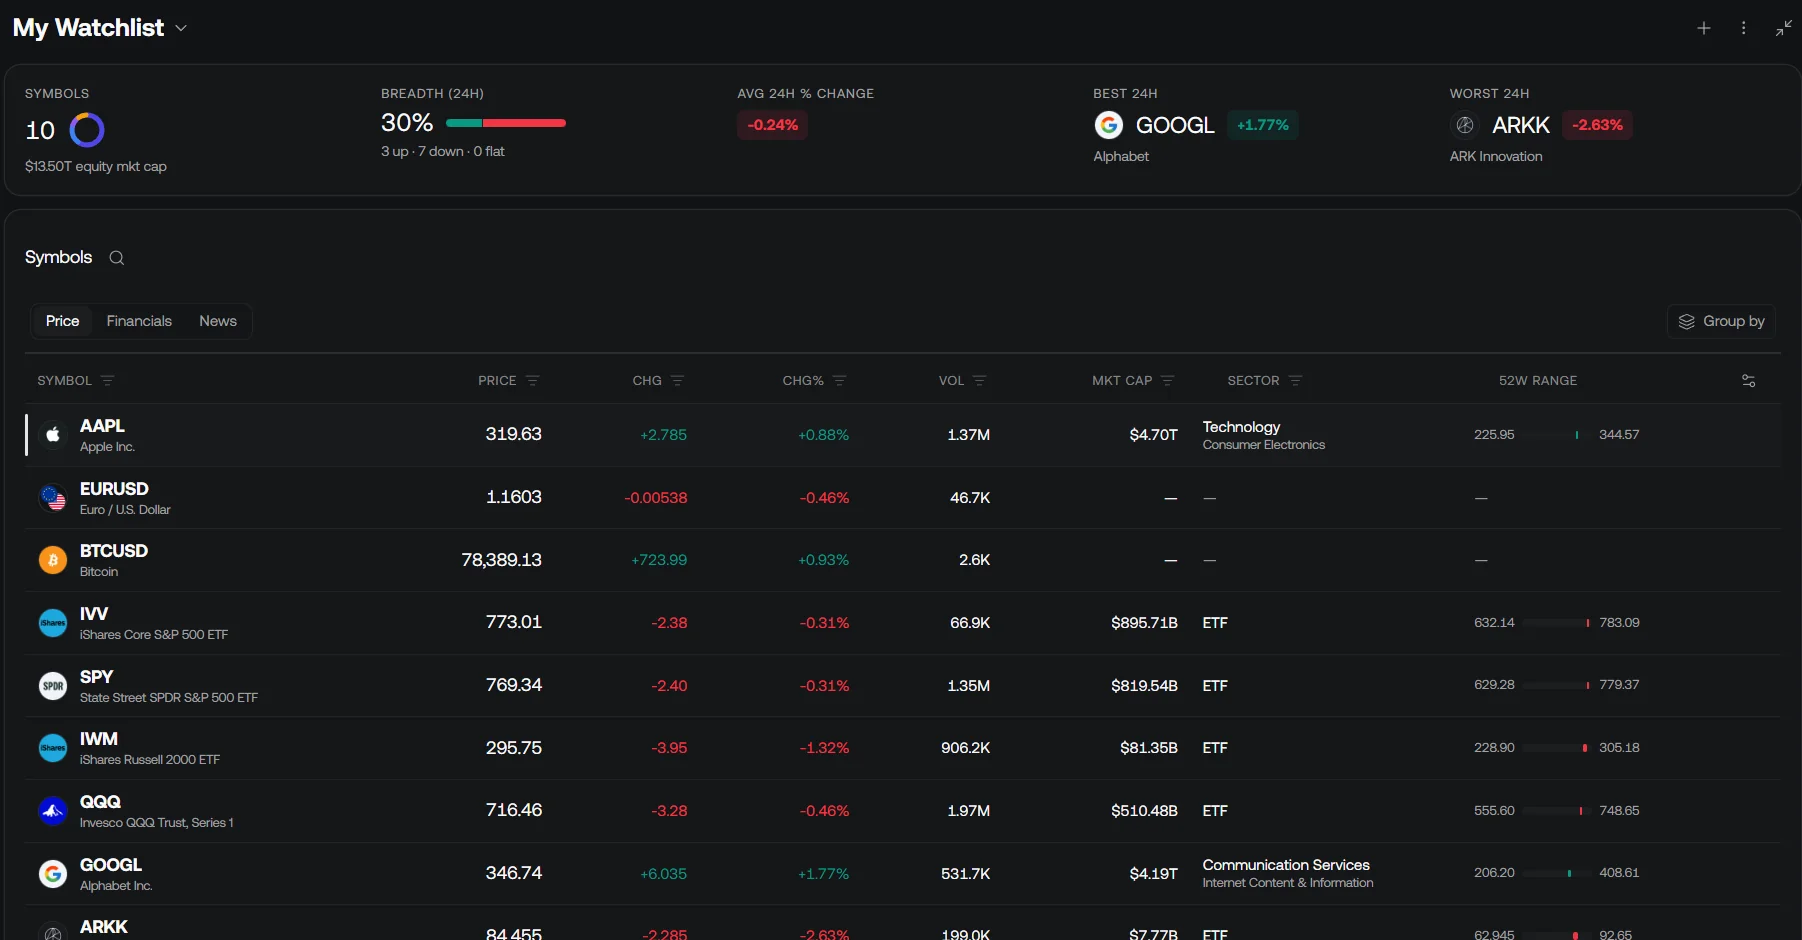
Use the LuxAlgo Watchlist to organize candidate symbols and review available market, financial and news information. Keep the float estimate’s source and date in your research notes. A list of symbols is not proof that the platform supplies a complete historical float database.
Inspect price and volume on LuxAlgo charts. Volume profiles and footprints describe executed activity where supported; they do not enumerate shareholders or show the entire supply of resting orders. The data documentation distinguishes chart and order-flow coverage. In particular, venue-specific U.S. equity order flow should not be treated as consolidated market volume.
Ask Quant, our coding agent, to implement an explicit chart-based rule, such as a completed-bar breakout with a defined volume filter. Review the code, run the strategy and configure capital, order size, commission and slippage. Inspect the backtest summary and Trades Log and test an untouched period.
A genuine historical float filter needs point-in-time float data. Inserting today’s float into every past bar can misclassify companies after offerings, repurchases or splits. If that history is unavailable, label the test as a price-and-volume experiment rather than claiming it validates a low-float strategy. A generated script also does not automatically account for stock-borrow availability, trading halts or a changing universe of delisted stocks.
When choosing external research software, compare field definitions, update frequency, corporate-action handling and historical coverage before brand names or plan tiers. Screening, charting and execution solve different problems. A current float field may support today’s research while remaining unsuitable for a historical backtest.
Practical Takeaways
Use float to understand the scale and structure of tradable ownership. Use outstanding shares for the relevant ownership and valuation calculations. Then check actual market conditions: a turnover ratio is not a directional signal, a high float is not a safety rating, and a lower share count after a corporate action does not prove the stock became more valuable.
A disciplined process combines dated ownership data, correctly matched volume, a specific trading hypothesis and realistic execution assumptions. LuxAlgo can support the chart research and rule testing, while issuer filings and clearly defined external data provide the share-count evidence.
Read next