Stocks to Trade: Picks Breakdown
Lists of "stocks to trade this year" age badly. The names, the price levels and the earnings forecasts they rest on are stale within a quarter, and a reader who arrives a year later inherits a list of picks with none of the reasoning that produced them. This guide takes the opposite approach. It breaks down the process behind a pick: what kinds of stock you are choosing between, how to build a candidate list, which fundamental and technical filters narrow it, how order types and position sizing turn a candidate into a trade, and how to run the whole routine in Quant Charts, including a Quant backtest of the screening rule itself. It names no tickers and quotes no price targets, because those are the parts that go stale.
What You Are Choosing Between
A stock is a share of ownership in a company. Investor.gov's overview of stocks describes the two main kinds. Common stock carries voting rights and any dividends the board declares. Preferred stock usually has no vote but receives dividends ahead of common stock and ranks ahead of it if the company is liquidated. Almost everything an active trader screens is common stock, because that is where the trading volume is.
The same overview groups stocks by character. Growth stocks have earnings growing faster than the market average and rarely pay dividends. Income stocks pay dividends consistently. Value stocks trade at a low price-to-earnings ratio, sometimes because the market has soured on them. Blue-chip stocks are large, well-known companies with a long record. Stocks are also grouped by market capitalization, which Investor.gov defines as the share price multiplied by the number of shares outstanding: large-cap, mid-cap, small-cap, microcap and, at the bottom, penny stocks, which Investor.gov describes as highly speculative with little or no earnings.
These labels matter for a trader because they set expectations. A large-cap growth stock and a microcap turnaround respond to news differently, trade with different liquidity and need different stop distances. The first filter in any selection process is deciding which of these groups the strategy is designed for, before a single chart is opened.
Building the Candidate List
A selection process needs a universe to select from. The practical unit is a watchlist: a saved list of symbols that loads onto the chart with one click. Keep separate lists for separate routines, for example one per sector, one per strategy or one for earnings season, so that each list answers a single question.
Two sources feed a candidate list without relying on anyone else's picks. The first is public disclosure. Investor.gov's guide to researching investments points to EDGAR, the SEC's filing database, and explains how to read a 10-K annual report, an 8-K current report and the insider-transaction Forms 3, 4 and 5. A company that is not registered with the SEC is, in Investor.gov's words, a possible red flag. The second source is the market itself: symbols that show unusual volume, new highs or lows, or a sector move. Both sources produce candidates, not trades. The filters below decide which candidates survive.
Fundamental Filters
Fundamental filters answer whether the business behind the ticker is the kind the strategy wants. The useful ones are simple ratios that can be read from a data table rather than modelled from scratch.
- Price-to-earnings ratio. Investor.gov defines the P/E ratio as the current share price divided by current earnings per share, a way of gauging whether the price is high or low compared with the company's past or with other companies. A low P/E is what defines a value stock; a high one is common in growth names. Neither is good or bad on its own, so use P/E to sort a list into groups rather than to rank it.
- Earnings and revenue growth. Year-over-year change in revenue, net income and earnings per share separates growing businesses from shrinking ones. Growth stocks, by Investor.gov's definition, are the ones where earnings grow faster than the market average.
- Dividend and yield. A consistent dividend marks an income stock. Traders who hold overnight also need to know the ex-dividend date, because the share price adjusts on it.
- Beta. A measure of how much the stock has moved relative to the market. High-beta names suit strategies that need movement; low-beta names suit strategies that need a calm chart.
- Market capitalization and sector. These are grouping fields more than filters: they keep a list from silently mixing a megacap with a microcap, or a utility with a semiconductor.
None of these filters carries a magic threshold. A rule such as "P/E below 15" is a choice about which group to trade, and the right way to test the choice is to backtest a strategy on that group rather than to accept the number from an article.
Technical Filters
Technical filters answer whether the chart is doing what the strategy needs right now. Four ideas from the LuxAlgo Library cover most selection rules.
- Trend structure. A rising sequence of higher highs and higher lows, or a falling sequence of lower highs and lower lows, is the simplest statement of trend. A list can be sorted into trending and ranging names before any indicator is applied.
- Breakouts. The Library's breakout entry defines a breakout as a close beyond a boundary the market had been respecting, such as a range extreme, a prior session high or a channel line. Orders cluster around those boundaries, which is why genuine breaks often arrive with a burst of activity, and why the failed version, the false breakout, snaps back when the activity does not come.
- Relative volume. Raw volume means nothing across symbols, because ten million shares is quiet in one name and historic in another. The relative volume entry expresses today's volume as a multiple of the symbol's own baseline, such as the prior 20 sessions, so a reading of 1 is ordinary and 3 is three times usual participation. That ratio is how a whole watchlist can be ranked by unusual activity.
- Volatility. The ATR entry describes Average True Range as the average of each bar's true range, which counts gaps by anchoring to the prior close. Dividing ATR by price gives ATR percent, which makes volatility comparable across a list. Volatility is a filter in both directions: a strategy needs enough movement to pay for costs, and not so much that the stop is hit by noise.
The table below turns those ideas into a screening checklist. The wording is deliberately qualitative. The exact lookbacks and multiples belong in a backtest, where they can be tested rather than asserted.
| Question | Where to look | What passes |
|---|---|---|
| Is this the type of stock the strategy was built for? | Market cap, sector, growth or value character | Matches the group the rule was tested on |
| Is the business moving the right way? | Revenue, net income and EPS growth; P/E | Consistent with the strategy's thesis |
| Is the chart trending or ranging? | Sequence of swing highs and lows | The structure the strategy trades |
| Is anyone participating? | Relative volume against the symbol's baseline | Above normal on the day of the setup |
| Can the stop survive normal noise? | ATR or ATR percent | Stop distance is a multiple of ATR, not a round number |
| Is there a boundary to trade against? | Range extremes, prior highs and lows | A defined level for entry and invalidation |
From Candidate to Order
A stock that passes every filter still has to be bought and sold, and the order type decides what "buy" means. Investor.gov's page on types of orders describes the three basic ones.
- A market order buys or sells immediately. It guarantees execution but not price, and it generally fills at or near the current ask for a buy or the bid for a sell. Investor.gov notes that the last traded price is not necessarily the price a market order gets.
- A limit order buys or sells at a specified price or better. A buy limit fills only at the limit or lower; a sell limit only at the limit or higher. The trade-off is that it may never fill.
- A stop order, also called a stop-loss order, becomes a market order once the stock trades at the stop price. A sell stop below the market protects a long position; a buy stop above the market protects a short. Investor.gov's glossary adds the caveat that a short-term fluctuation can trigger the stop, and that the fill can differ from the stop price in a fast market.
The selection process should say which order type goes with which setup. A breakout entry is often a buy stop just above the boundary, so it fills only if the break happens. A pullback entry is often a limit order at the level. The protective stop is placed at the invalidation point identified in the technical filter, at a distance measured in ATR rather than in a fixed percentage.
Position Sizing
Sizing is where risk becomes a number. The Library's fixed fractional entry describes the most common rule: risk the same fraction of current equity on every trade, and back-solve the share count from the stop. Its worked example is a $50,000 account risking 1 percent, which commits $500; with a stop $2 away, that is 250 shares. Because the fraction applies to current equity, dollar risk shrinks through a losing streak and grows after gains.
The same entry is explicit about what the rule does not do. It says nothing about where the stop belongs, and a gap or slippage can take more than the budgeted fraction. That is why the stop distance comes from the volatility filter and the size comes from the stop, in that order. Reversing the order, choosing a share count first and fitting a stop to it, is the mistake that turns a good candidate into an oversized position.
Why Published Picks Age Badly
Any article that names a stock also fixes a date. The P/E it quotes changes with every earnings report and every price move. A price level that was resistance becomes support or becomes irrelevant. A forecast for the year is a single analyst's estimate and is revised many times before the year ends. Investor.gov's warning that stock prices move down as well as up, and that there is no guarantee a company will grow, applies to every pick regardless of how well the write-up was argued.
A process does not have this problem. The same filters, run on the same watchlist a year later, produce a fresh list of candidates that reflects current data. The only things that should be written down permanently are the rules, the reasons for them and the backtest that supports them.
Where Quant Charts Fits
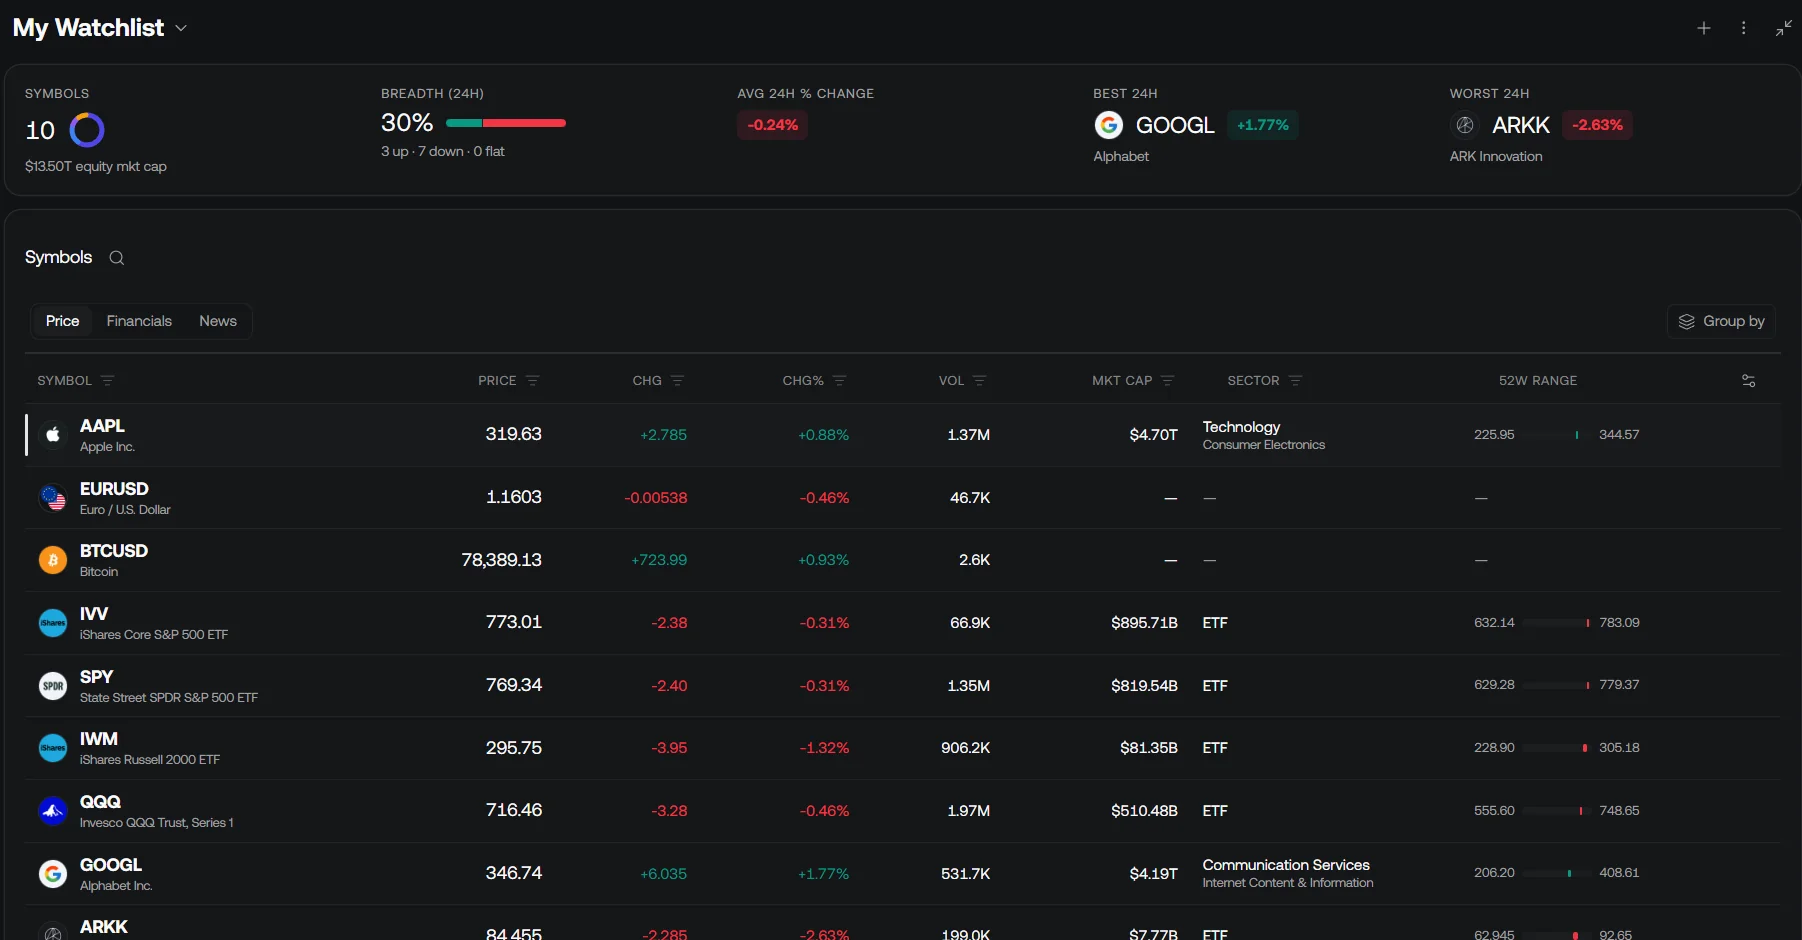
The watchlist is the candidate list. In Quant Charts, the docked watchlist panel holds the symbols you follow and loads any of them onto the active chart with a click. Add symbols through Symbol Search, keep separate lists for separate routines and drag rows into your own order. Every plan includes US equities and ETFs from Cboe EDGX plus crypto spot and perpetuals; the Free plan allows two lists of ten symbols, and paid plans allow unlimited lists of up to 500 symbols each.
Advanced view is the fundamental screen. Maximize the panel and the whole list appears as a data table with three tabs. Price shows price, change, volume, market cap, sector and the 52-week range. Financials shows revenue, net income, EPS, P/E, dividend per share, yield and beta, with year-over-year growth where it exists. News is a headline feed for the list. Column headers sort, header filters narrow by number or checklist, Group by clusters rows by asset type, sector or exchange, and Sections let you keep your own groupings, for example "passed fundamentals" and "watching". The Allocation panel shows asset-class and sector exposure for the list.
Indicators cover the technical filters. Click Indicators in the chart topbar to add relative volume, ATR or any of the Library's breakout implementations to the active chart, and star the ones you reuse so they sit in Favorites. In a multi-chart layout, click the target cell first; the watchlist always feeds the active cell.
The video below shows how indicators are added to a chart in Quant Charts.
Quant backtests the screening rule. Describe the rule to Quant, our coding agent, in plain language, for example buying when the stock closes above its 20-day high with relative volume above two and exiting at a stop two ATRs below entry or after ten bars. Quant writes the Pine Script; open Code to inspect it, then click Run. The Backtest Summary reports net profit, trade count, win rate, max drawdown and profit factor. Set commission and slippage in the strategy's Properties so the result reflects trading costs. Run the same strategy on several symbols from the list and the ones where the rule has no edge drop out, which is a more honest filter than any published pick.
The Journal grades the process. Every plan includes the Journal, which turns broker fills or imported trades into round trips and breaks down results by symbol, side, hold time and time of day. A selection process that looks good on paper but loses in one sector or one session shows up there, and the filter can be adjusted. No LuxAlgo tool places orders; the Journal records what you traded elsewhere.
FAQs
What is the difference between common and preferred stock?
Common stock carries voting rights and receives dividends when declared. Preferred stock usually has no vote but is paid dividends before common stock and ranks ahead of it if the company is liquidated, according to Investor.gov.
What does a P/E ratio tell a trader?
Investor.gov defines it as share price divided by earnings per share, a gauge of whether the price is high or low relative to the company's past or to peers. It is best used to group a list into value and growth names, not to rank it.
Why use relative volume instead of volume?
Raw volume is not comparable across stocks. Relative volume divides current volume by the symbol's own baseline, so a reading of 3 means three times normal participation in any name, which lets a whole watchlist be ranked on one scale.
What is a stop order?
An order that becomes a market order once the stock trades at the stop price. A sell stop below the market limits a loss on a long position. Investor.gov notes that short-term fluctuations can trigger it and that the fill may differ from the stop price.
How is position size calculated with a fixed fraction?
Multiply current equity by the risk fraction to get the dollar risk, then divide by the distance from entry to stop. The Library's example is a $50,000 account risking 1 percent with a $2 stop, which gives 250 shares.
Can Quant Charts screen stocks by fundamentals?
The watchlist Advanced view shows revenue, net income, EPS, P/E, dividend, yield and beta for every stock on a list, with sorting, filters, grouping and sections. Quant can then backtest a rule on the survivors and report win rate, max drawdown and profit factor.
References
LuxAlgo Resources
- Breakout, Relative Volume, ATR and Fixed Fractional concepts (LuxAlgo Library)
- Watchlist and Advanced view (LuxAlgo Docs)
- Indicators and Data (LuxAlgo Docs)
- What is Quant and Making strategies with Quant (LuxAlgo Docs)
- Journal (LuxAlgo Docs)
External Resources
- Stocks (Investor.gov)
- Types of Orders (Investor.gov)
- Price-earnings (P/E) Ratio, Market Capitalization and Stop Order (Investor.gov Glossary)
- Researching Investments (Investor.gov)
- Search EDGAR filings (SEC)
This article is educational and is not a recommendation to buy or sell any security. Stock prices can fall as well as rise.
Read next